
Topic:
Property & Casualty
Article content
Why the settlement doesn’t always match the damage, and what makes these disputes complicated
After a property loss, an insurance payment can bring real relief to the property owner. That relief fades fast when the amount turns out to be too small to actually complete the repairs! A homeowner in Miami-Dade county may receive an estimate that addresses the visible damage while leaving open questions about related materials, labor, code requirements, or damage in areas nobody even noticed at first.
An underpaid claim isn’t always the result of one obvious mistake. Gaps tend to open up because the insurer and the property owner hold different views of what was damaged, what work is needed, or what that work should cost. Understanding the gap starts with understanding what the estimate actually covers.
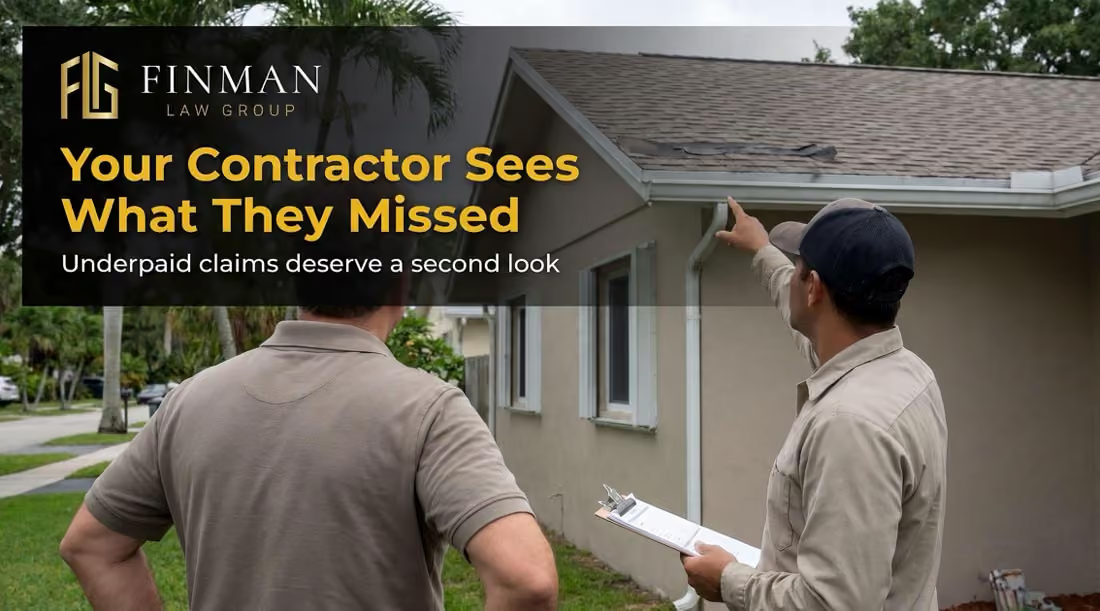
A repair estimate is built from measurements, material selections, labor assumptions, photographs, and the observed condition of the building. When any of those details are incomplete or disputed, the estimate can land far from what a contractor believes the job requires.
Water entering through a damaged roof, for example, may affect insulation, ceiling materials, interior finishes, and flooring, which makes a visible ceiling stain only one piece of the loss. A storm-damaged window raises its own questions about the surrounding trim and water intrusion. The older homes in neighborhoods like Coral Gables, Miami Shores, and Little Havana add complexity when materials need matching, and condominium repairs often cross into connected areas. Labor and material costs vary by project and location too, and a scope that doesn’t account for the actual work rarely lines up with a realistic repair plan.
Miami-Dade holds older single-family homes in Hialeah and Westchester, newer construction out in Doral and Homestead, high-rise condominiums along Brickell, Miami Beach, and Aventura, and mixed-use buildings throughout the county. Each presents different challenges after a loss. In a condominium, damage can involve both the individual unit and shared building components, which raises questions about which portions belong to the unit owner, which belong to the association, and how the governing documents and insurance policies apply. In a single-family home in Kendall or Cutler Bay, the roof assembly, stucco, windows, plumbing, and interior finishes may all be part of the repair conversation. South Florida’s heavy rain, wind-driven water, and high humidity complicate the assessment further, and damage that wasn’t fully documented early tends to get harder to evaluate later.
A disagreement over a claim amount can center on the cause of the damage, the extent of the affected areas, the repair methods, or the cost, and there may also be questions about policy limits, deductibles, exclusions, depreciation, and other provisions. A difference between estimates doesn’t automatically mean the insurer acted improperly.
The documents usually tell the story: the policy, the insurer’s estimate, photographs, inspection records, contractor estimates, invoices, and the claim communications. Comparing them side by side shows where the scopes part ways. One estimate includes replacing a damaged material while another assumes a smaller repair, or one omits an area the contractor’s scope plainly shows. The policy language and the facts decide what’s covered, and not every repair item necessarily is.
People who come through these disputes well oftentimes have an organized records such as the follow:
None of it guarantees an outcome, but it makes the claim history far easier to follow, and it also makes the gap between what was paid and what is still necessary more apparent.
A claim that looks underpaid deserves a careful review of both the estimate and the policy, and the right questions depend on the property type, the source of the damage, the repairs required, and the coverage involved. From Miami Beach high-rises to family homes in Homestead, Finman Law Group handles property insurance claim disputes all across Miami-Dade, including disagreements over damage estimates and claim payments, and can review your unique circumstances.
If your Miami-Dade property claim came back underpaid, contact Finman Law Group for a free evaluation of your situation.


Learn what injured motorcycle riders in Orlando and Central Florida should know, from common crash causes on I-4 and busy tourist corridors to liability, insurance coverage, and injury claims.
How sidewalk conditions, maintenance responsibilities, and the circumstances of a fall factor into a Tampa personal injury claim.
How unsafe conditions at Houston concerts and live events can lead to injury claims, including crowd hazards, poor lighting, and unsecured equipment.