Business Property Damage Claims in the Greater Houston Area

Business Property Damage Claims in the Greater Houston Area

Article content

When storms, burst pipes, or electrical failures hit your business, the claim shouldn't become a second disaster

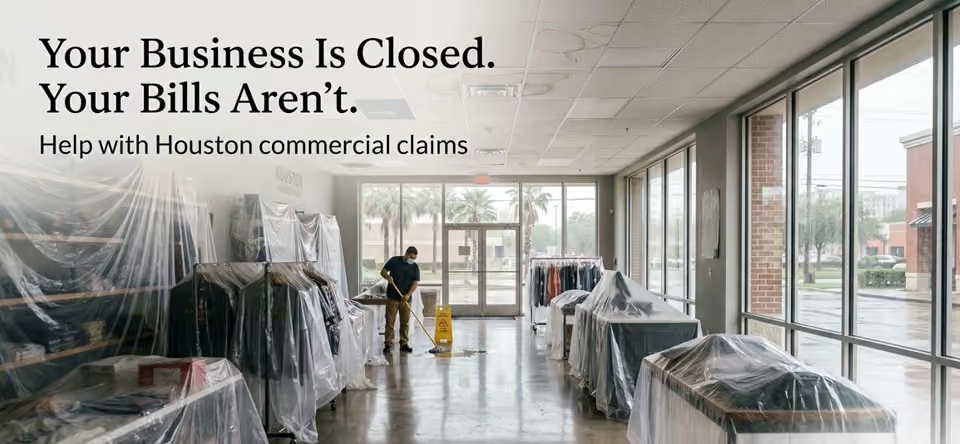
Businesses across the Greater Houston area face a wider range of property damage risks than almost anywhere in the country. Gulf storms batter roofs, aging pipes burst inside walls, electrical failures knock out equipment, vandalism strikes overnight, and structural issues develop quietly until they can't be ignored. When damage hits, the clock starts running in a way homeowners never quite experience. Every day a restaurant sits closed, a shop can't open, or an office stays unusable, revenue stops while rent, payroll, and loan payments keep right on going. Owners expect their insurers to step in quickly. Too often, they face delays, underpayments, and confusing claim decisions instead, and for a business, that treatment doesn't just cost money. It threatens livelihoods.

The Damage Houston Businesses Face

Houston's climate and infrastructure create conditions where commercial damage happens frequently, and a few types account for most claims:

  • Storm-related roof leaks that let water into offices, storefronts, and warehouses, soaking inventory and inviting interior moisture and mold
  • Electrical failures that damage equipment, disrupt operations, and sometimes trace back to storm surges or aging building systems

Burst pipes add sudden flooding to the list, vandalism brings broken glass and forced-entry damage, and structural issues from shifting clay soil and years of weather compound everything else. The damage rarely stays in one category either. A single roof leak can affect the structure, the equipment underneath it, the inventory on the shelves, and the spaces customers see, and each piece gets valued differently when the claim gets filed. That's exactly where things start to stall.
What Business Owners Typically Do After Damage

Owners who navigate these claims best act quickly on several fronts at once. They take photos of exterior and interior damage immediately, before any cleanup or repairs begin, because proof disappears with the first dumpster and the first patch. They request contractor estimates from commercial companies, putting realistic Houston-market repair costs on paper, since insurer estimates frequently undervalue what repairs actually cost. They preserve financial records too, because business interruption losses live and die on proof of normal revenue, and sales reports and monthly statements establish exactly what the closure is costing. Reasonable protective steps, tarping, board-ups, water extraction, round out the effort, with every receipt saved. Each piece of that record strengthens the claim and shortens the disputes, and for a business, shorter disputes mean sooner reopenings.

The Human Impact

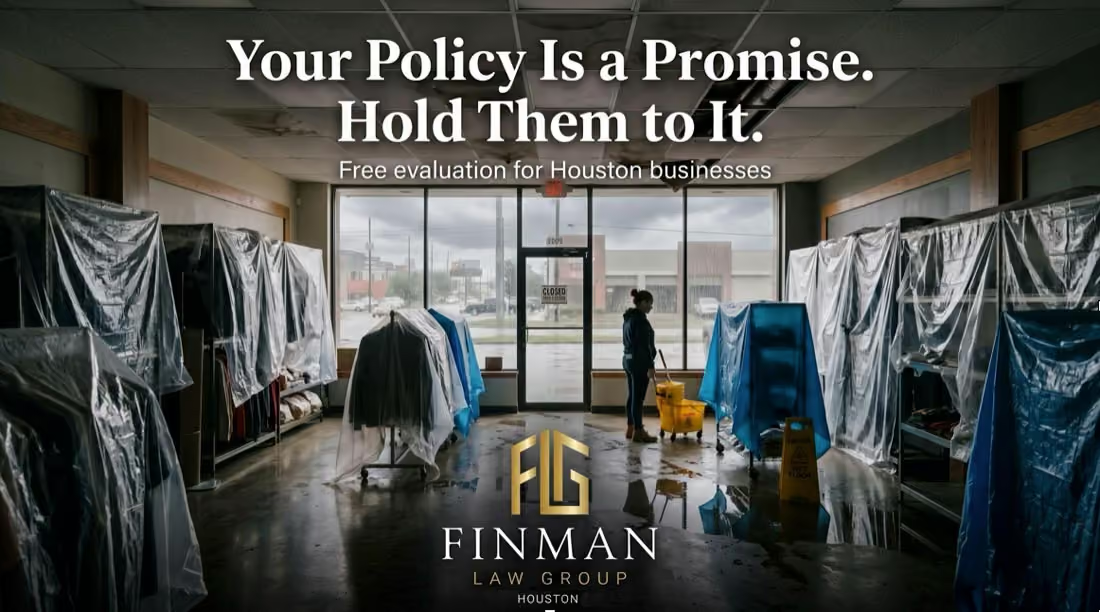
Property damage affects far more than a building. Business owners worry about lost revenue, employee safety, and customer trust, and behind every commercial claim is an owner carrying weight most people never see. Employees calling about their hours. Customers wondering when doors reopen. Vendors still expecting payment while the registers sit silent. When insurers offer low settlements or question the cause of the damage, it adds frustration to an already crushing situation. Imagine arriving at your business after a storm and finding water pooling on the floor, damaged inventory, and electrical issues, then facing delays and unclear answers from the company that's supposed to help. That experience is common across Houston, and owners deserve better. They deserve support that feels steady and compassionate while they fight to keep their doors open.

Getting Back to Business

Commercial claims are complex, and insurers know most owners are too busy managing the crisis to fight line by line. Policies layer building coverage, contents and equipment, and business interruption provisions in technical language that can obscure what's actually owed. Understanding how these claims generally work, what documentation carries weight, and when experienced support makes sense can change both the timeline and the outcome, and it helps make sure structural damage, equipment loss, and interrupted income don't get ignored. The goal isn't just a fair settlement. It's getting your doors open, your people working, and your customers back!

If your Greater Houston business suffered property damage and the claim is moving slowly or coming up short, Finman Law Group can help you pursue a fair and complete recovery. Reach out today for a free evaluation.‍

When storms, burst pipes, or electrical failures hit your business, the claim shouldn't become a second disaster

Businesses across the Greater Houston area face a wider range of property damage risks than almost anywhere in the country. Gulf storms batter roofs, aging pipes burst inside walls, electrical failures knock out equipment, vandalism strikes overnight, and structural issues develop quietly until they can't be ignored. When damage hits, the clock starts running in a way homeowners never quite experience. Every day a restaurant sits closed, a shop can't open, or an office stays unusable, revenue stops while rent, payroll, and loan payments keep right on going. Owners expect their insurers to step in quickly. Too often, they face delays, underpayments, and confusing claim decisions instead, and for a business, that treatment doesn't just cost money. It threatens livelihoods.

The Damage Houston Businesses Face

Houston's climate and infrastructure create conditions where commercial damage happens frequently, and a few types account for most claims:

  • Storm-related roof leaks that let water into offices, storefronts, and warehouses, soaking inventory and inviting interior moisture and mold
  • Electrical failures that damage equipment, disrupt operations, and sometimes trace back to storm surges or aging building systems

Burst pipes add sudden flooding to the list, vandalism brings broken glass and forced-entry damage, and structural issues from shifting clay soil and years of weather compound everything else. The damage rarely stays in one category either. A single roof leak can affect the structure, the equipment underneath it, the inventory on the shelves, and the spaces customers see, and each piece gets valued differently when the claim gets filed. That's exactly where things start to stall.

What Business Owners Typically Do After Damage

Owners who navigate these claims best act quickly on several fronts at once. They take photos of exterior and interior damage immediately, before any cleanup or repairs begin, because proof disappears with the first dumpster and the first patch. They request contractor estimates from commercial companies, putting realistic Houston-market repair costs on paper, since insurer estimates frequently undervalue what repairs actually cost. They preserve financial records too, because business interruption losses live and die on proof of normal revenue, and sales reports and monthly statements establish exactly what the closure is costing. Reasonable protective steps, tarping, board-ups, water extraction, round out the effort, with every receipt saved. Each piece of that record strengthens the claim and shortens the disputes, and for a business, shorter disputes mean sooner reopenings.

The Human Impact

Property damage affects far more than a building. Business owners worry about lost revenue, employee safety, and customer trust, and behind every commercial claim is an owner carrying weight most people never see. Employees calling about their hours. Customers wondering when doors reopen. Vendors still expecting payment while the registers sit silent. When insurers offer low settlements or question the cause of the damage, it adds frustration to an already crushing situation. Imagine arriving at your business after a storm and finding water pooling on the floor, damaged inventory, and electrical issues, then facing delays and unclear answers from the company that's supposed to help. That experience is common across Houston, and owners deserve better. They deserve support that feels steady and compassionate while they fight to keep their doors open.

Getting Back to Business

Commercial claims are complex, and insurers know most owners are too busy managing the crisis to fight line by line. Policies layer building coverage, contents and equipment, and business interruption provisions in technical language that can obscure what's actually owed. Understanding how these claims generally work, what documentation carries weight, and when experienced support makes sense can change both the timeline and the outcome, and it helps make sure structural damage, equipment loss, and interrupted income don't get ignored. The goal isn't just a fair settlement. It's getting your doors open, your people working, and your customers back!

If your Greater Houston business suffered property damage and the claim is moving slowly or coming up short, Finman Law Group can help you pursue a fair and complete recovery. Reach out today for a free evaluation.‍

Additionally Reads

When a Small Part Causes Big Property Damage

When a Small Part Causes Big Property Damage

How defective building components cause property damage, why responsibility gets disputed, and what makes these claims complicated for property owners.
When a Rental Property Becomes Unsafe

When a Rental Property Becomes Unsafe

Learn how unsafe apartment conditions can lead to injury claims and why maintenance records, notice, and control of the property shape the answer.
Before You Accept an Injury Settlement Offer

Before You Accept an Injury Settlement Offer

Practical questions to think through before accepting a personal injury settlement, including medical care, lost income, documentation, and release terms.